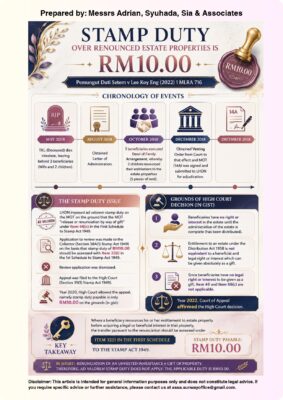
Case : Pemungut Duti Setem v Lee Koy Eng (2022) 1 MLRA 716
May 2018, TKL (Deceased) dies without leaving a Will and left 3 beneficiaries (Wife and 2 children).
August 2018, obtained Letter of Administration.
October 2018, 3 beneficiaries executed Deed of Family Arrangement, whereby 2 children gave up (renounced) their entitlement to the estate properties (5 pieces of land).
December 2018, obtained Vesting Order from Court to that effect and MOT (14A) was signed and submitted to LHDN for adjudication.
LHDN imposed ad valorem stamp duty on the MOT on the ground that the MOT “release or renunciation by way of gift under item 66(c) in the First Schedule to Stamp Act 1949.
Application to review was made to the Collector (Section 38A(1) Stamp Act 1949) on the basis that stamp duty of RM10.00 should be assessed with item 32(i) in the 1st Schedule to Stamp Act 1949.
Review application was dismissed. Appeal was filed to the High Court (Section 39(1) Stamp Act 1949).
Year 2020, High Court allowed the appeal, namely stamp duty payable is only RM10.00 on the grounds (in gist):-
- Beneficiaries have no right or interest in the estate until the administration of the estate is complete (has been distributed)
- Entitlement to an estate under the Distribution Act 1958 is not equivalent to a beneficial and legal right or interest which can be given absolutely as a gift.
- Since beneficiaries have no legal right or interest to be given as a gift, Item 46 and Item 66(c) are not applicable
Year 2022, Court of Appeal affirmed the High Court decision.
So based on this decision, stamp duty payable over estate properties that has been renounced by the respective beneficiaries should be assessed with item 32(1) in the 1st Schedule to Stamp Act 1949, namely RM10.00
The key principles and decision are summarised in the infographic below.